1,200 doors · 14,400 cases in the current sheet; pending confirmation.
Assumption — finalizingEveryday SRP · feel free CLASSIC is estimated around $8.00.
Assumption — finalizing$55 blended case less cost, sales trade, marketing and SG&A.
Assumption — finalizingTwo legal footprints, one distributor conversation.
2027 plan
From 1,200 doors this quarter to 10,350 by the end of 2027.
Justin's Year 1 plan from the shared sheet. All figures remain working assumptions until Ernie and Kyle finalize them.
4,536,000 units · $55.00 blended case
Assumption — finalizingKyle to update
Assumption — finalizing12 units per case
Assumption — finalizingAfter cost, trade, marketing and SG&A · sheet calls this net revenue
Assumption — finalizing2026 Q4
GA, PA, NJ
- Rolling doors
- 1,200
- Cases / door / month
- 4
- Cases
- 14,400
- Units
- 172,800
2027 Q1
IL, FL, RnR, WildSide
- Rolling doors
- 3,600
- Cases / door / month
- 4
- Cases
- 43,200
- Units
- 518,400
2027 Q2
VA, WI, NC, TBD
- Rolling doors
- 5,400
- Cases / door / month
- 4
- Cases
- 64,800
- Units
- 777,600
2027 Q3
TBD
- Rolling doors
- 7,650
- Cases / door / month
- 5
- Cases
- 114,750
- Units
- 1,377,000
2027 Q4
TBD
- Rolling doors
- 10,350
- Cases / door / month
- 5
- Cases
- 155,250
- Units
- 1,863,000
| Measure | 2026 Q4 | 2027 Q1 | 2027 Q2 | 2027 Q3 | 2027 Q4 | 2027 total |
|---|---|---|---|---|---|---|
| Markets | GA, PA, NJ | IL, FL, RnR, WildSide | VA, WI, NC, TBD | TBD | TBD | |
| Rolling retail doors | 1,200 | 3,600 | 5,400 | 7,650 | 10,350 | 10,350 |
| Velocity (cases / door / month) | 4 | 4 | 4 | 5 | 5 | |
| Cases | 14,400 | 43,200 | 64,800 | 114,750 | 155,250 | 378,000 |
| Units | 172,800 | 518,400 | 777,600 | 1,377,000 | 1,863,000 | 4,536,000 |
| Revenue | $792K | $2.38M | $3.56M | $6.31M | $8.54M | $20.79M |
Spend per case
- Blended case price
- $55.00
- COGS + freight · Pricing tab
- ($32.04)
- Trade spend (12%) — sales line
- ($6.60)
- Marketing spend (12%) — incl. POS
- ($6.60)
- SG&A (7%)
- ($3.85)
- Net per case
- $5.91
Blended $55 case less $32.04 cost, 12% sales trade, 12% marketing and 7% SG&A. The sheet's “net revenue” is actually the amount left after all four costs, not accounting net revenue.
Still open in the sheet
- Retail door counts and account-level forecast — Kyle to confirm
- 2027 Q2 lists WI, but the earlier legal-state screen excludes Wisconsin — confirm SKU and compliance before treating those doors as available
- Markets for 2027 Q3–Q4 and Q2's TBD market
- Ecommerce dollars per quarter
- COGS + freight per case — sheet still flags $32.04 for update
- The sheet's 28,200 'total doors' adds rolling quarter-end doors; it is not unique doors — use 10,350 year-end doors
Additional funded ask in this sheet: $0.00. This does not establish total working-capital needs.
Distributor opportunity
$423K / month
Illustrative distributor replenishment opportunity, not incremental revenue to add to the 2027 plan. Source: Napkin Math - Counter Culture.
Beyond 2027
FY2 and FY3 are not in this workbook.
The full model page shows every tab of the current sheet; no earlier three-year projections are presented as current.
The product
What we're putting on the shelf.
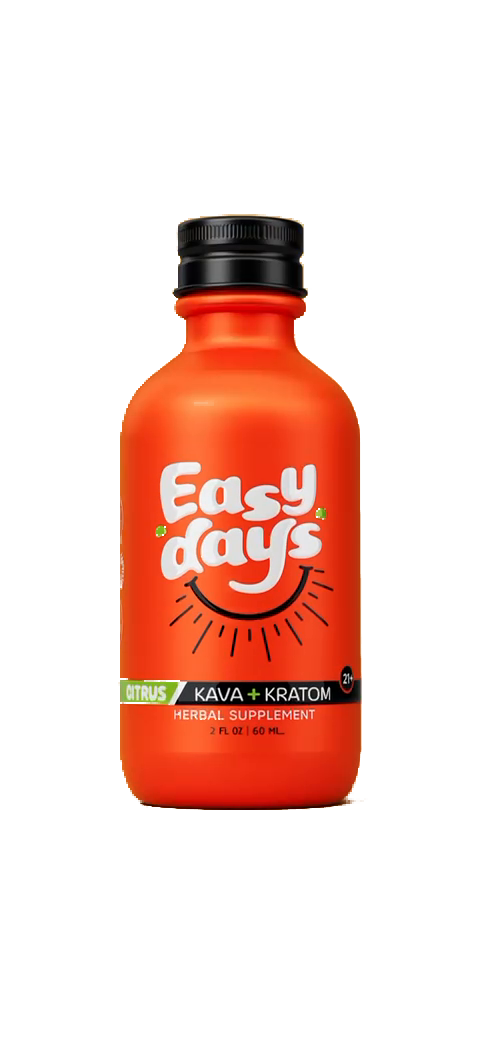
Kava + Kratom
Wind-down after the work is done
Noble kava root, water-extracted, lab-verified plain leaf kratom, third-party tested every lot.
Kava + Caffeine
Steadier, calmer kind of alert
Noble kava root only with a moderate caffeine dose. No kratom — sells where kratom cannot.
Where we attack
Where feel free (Botanic Tonics) is exposed.
Full disclosure on the front of the bottle
The category's biggest liability is labeling. Easy Days states Kava + Kratom plainly, 21+, with dose and warnings up front. That is a buyer-safety argument, not just a marketing line.
Two SKUs, two legal footprints
Kava + Caffeine holds shelf where kratom is restricted. A one-SKU competitor loses the door entirely; Easy Days keeps the account.
Lab-tested every lot, published
Third-party testing per lot, made available to the buyer. Matches the compliance bar the category leader had to build after the fact.
Creator Collective instead of paid category ads
16.5% attributed commission on a 21+ creator roster — acquisition cost scales with sales instead of front-loading media spend.
Interpretation based on public reporting and Botanic Tonics' own releases — see the investor page for sources.
Still open
What we owe each other this week.
| Item | Status | Owner |
|---|---|---|
| Q4 unit commitment | 172,800 units (14,400 cases, 1,200 doors) in the current sheet. Final pending door counts from Kyle. | Ernie + Kyle |
| Full sales forecast build | The sheet projects 378,000 cases in 2027; account-level forecast and market spend allocation still need confirmation. | Ernie + Kyle |
| Overall pricing model | Pricing tab (WIP): $9.99 everyday SRP / $7.99 promo 4x/yr, $5.00 wholesale, $5.50 to retail via DSD (24.24% margin), $2.67 unit COGS. | Ernie + Kyle |
| Confirmed COGS on RN | Pricing tab carries $2.67/bottle ($32.04/case). Awaiting landed-cost confirmation. | Ops |
| Trade spend envelope | Structure agreed (trade in sales, POS in marketing). Dollar envelope pending the forecast. | Sales + Marketing |
| Distributor target list | Counter Culture napkin math lists accounts and $423,250 monthly replenishment potential; conversion into the 2027 door plan is unconfirmed. | Sales |
| Field team pay plan | $25/hr + 10/20/30% commission tiers designed. Needs Shiky/Tom sign-off before hiring; door-opening bonus and reorder % still TBD. | Shiky / Tom, Kyle + Alex |
| Field team budget (Year 1) | $840K–$1.42M penciled for 9 reps, 3 regional managers, President of Sales. Largest line item; pending Alex. | Alex |